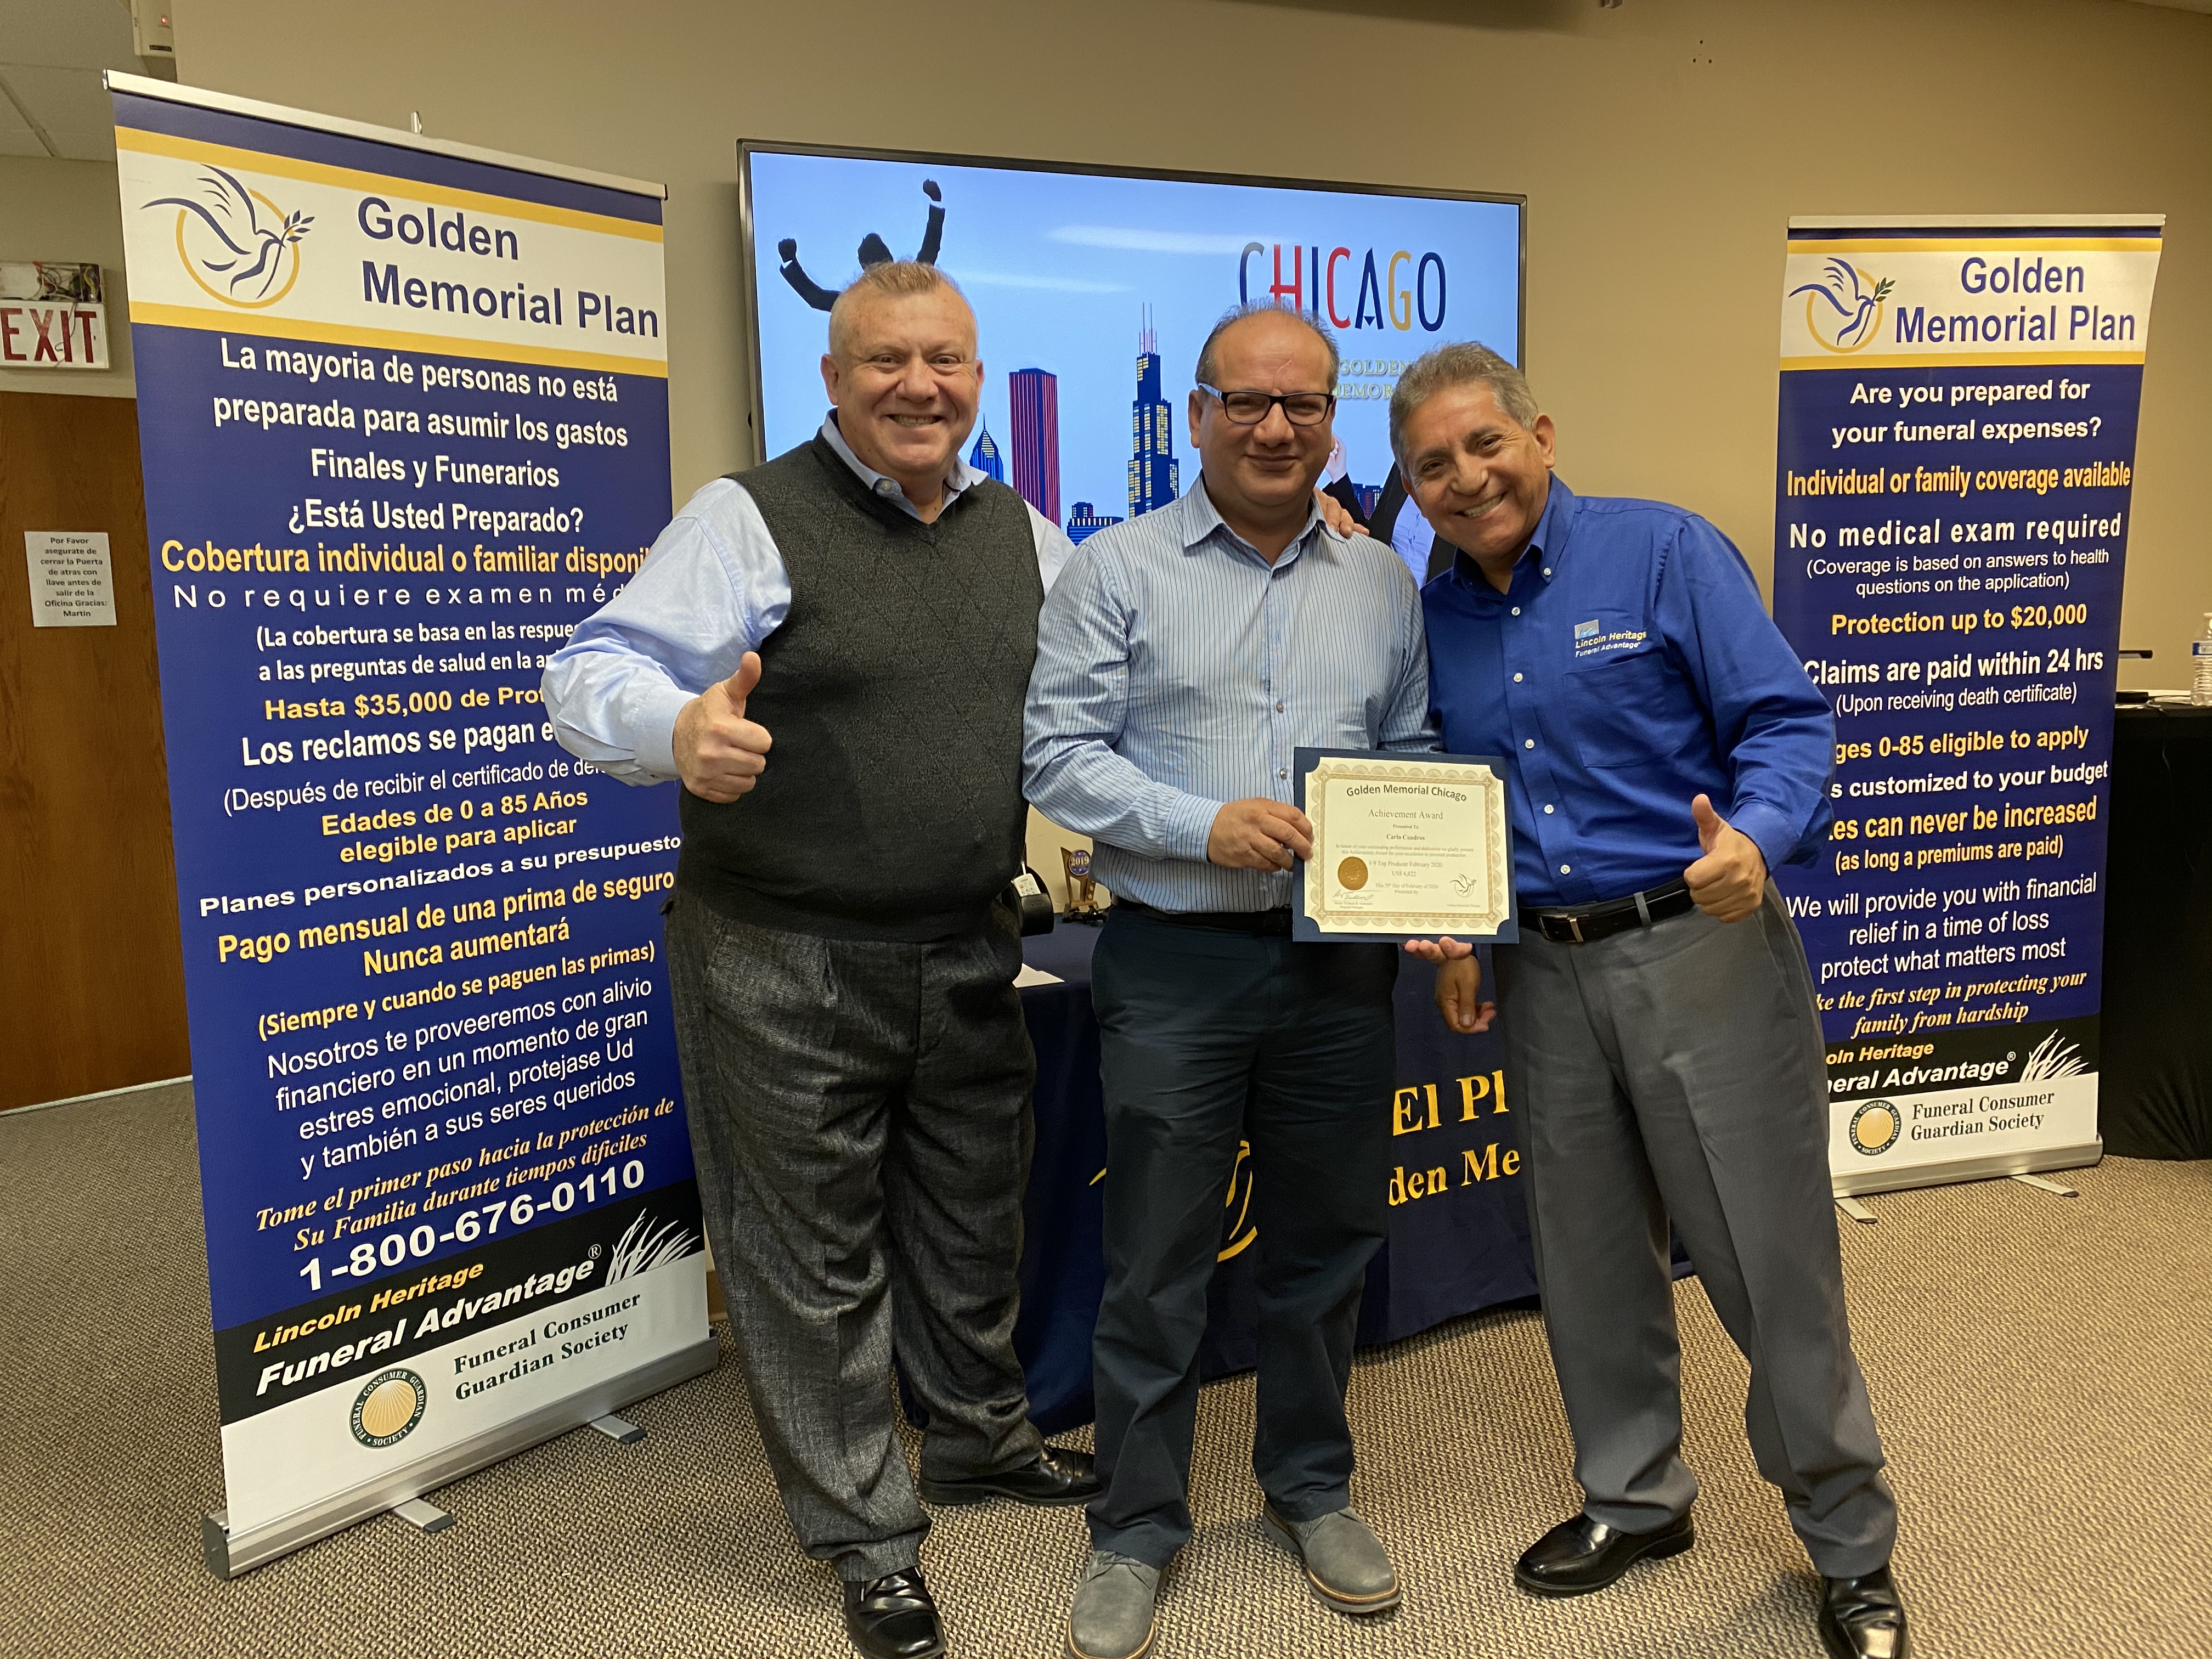
Golden Memorial Insurance in Illinois: What It Is and How Martin Eichhorn Helps Families Plan Ahead
Golden Memorial insurance refers to the life and final expense products that independent Golden Memorial agents, like Martin Eichhorn, help Illinois families compare, apply for, and keep in force over the years.
Golden Memorial is an insurance marketing organization whose independent licensed agents help families plan for end-of-life expenses, most often through small whole life policies designed to leave money behind for funeral costs and other final bills. When you work with Martin Eichhorn of the Eichhorn Group, you are working with a licensed Illinois agent who serves families across the Chicago suburbs and northern Illinois, walking you through plan options, answering questions in plain language, and helping you complete the application so the carrier can make its decision. If you would rather talk it through by phone, call (224) 578-2989 and Martin or a member of the team will help you sort out what kind of coverage fits your family — that call is a conversation, not a commitment.
Key Takeaways
- Golden Memorial insurance products are sold through independent licensed agents — Martin Eichhorn serves Illinois families as one of those agents.
- Final expense whole life policies are designed so a beneficiary can direct the benefit toward funeral costs, outstanding bills, and other end-of-life needs.
- The carrier, not the agent, sets the rates and approves or declines each application based on the health questions you answer.
- Agents are generally compensated by the carrier when a policy is placed; confirm any fee arrangement directly with the agent.
- Martin serves families across Illinois, including the Chicago suburbs, and you can reach him at (224) 578-2989.

Families searching "golden memorial insurance" are usually at one of two moments. Some are planning ahead for themselves, in their fifties or sixties, and want the details settled so their children are not left with funeral bills and guesswork. Others have just lost a parent or spouse and are trying to figure out what policy exists, who the beneficiary is, and what happens next. Martin Eichhorn has sat across the table from both kinds of families over years of serving Illinois clients through Golden Memorial, and the same truth comes up every time: the paperwork only gets easier when someone patient explains it once, clearly, in plain English.
What does a Golden Memorial agent actually do for you?
A Golden Memorial agent is an independent licensed insurance professional who represents the products in Golden Memorial's lineup and helps you compare them against your situation. That last word matters. A good agent does not start with a product. Martin starts with questions: who are you leaving money for, what do you want that money to cover, what does your health look like, what does your monthly budget realistically allow?
From there, the agent's job breaks into a few parts. Explaining how final expense whole life works and how the benefit gets paid to your beneficiary. Helping you fill out the application accurately, because health answers matter and errors cause delays. Submitting it to the carrier, which then sets the rate and makes the approval decision. And after the policy is in force, staying available — beneficiaries change, addresses change, questions come up years later. A policy you does not find is a policy that does not help anyone.
You can read more about how Martin works with families on the final expense insurance page, which walks through the same process step by step.
How does final expense coverage work?
Final expense insurance is a small whole life policy. It stays in force for life as long as premiums are paid, the benefit is paid to your named beneficiary tax-free as a death benefit, and the beneficiary decides how to use it. Most families direct it toward funeral and burial costs first, then medical bills, then whatever remains goes to the family.
Two structural details deserve attention. First, underwriting: these policies typically ask a short set of health questions rather than requiring a medical exam, and the carrier decides based on your answers whether to approve standard rates, modified rates, or decline. Second, grading: some policies have a waiting period on the full benefit for certain health conditions, and a straightforward agent will tell you plainly whether the policy you are considering has one and how it works.
The comparison above comes from Martin's own files after years of working with Illinois families on final expense planning. The pattern he sees repeatedly is simple to describe: many families have set aside some savings for a funeral, but the gap between what they have set aside and what a typical service actually costs is exactly where a final expense benefit does its work. Your own numbers will differ, which is precisely why sitting down with the actual figures — yours, not an average — is the useful move.
How do you know how much coverage is enough?
This is the question families get wrong most often, and it rarely goes in the direction you would expect. People tend to underestimate. They think about the funeral itself and forget the other costs that arrive in the same month: the utility bills still in the deceased's name, the credit card balances, the travel costs for family members coming in from out of state, the grave marker that is often priced separately from the service.
Martin's approach, refined over years of guiding Illinois families, is to list every expected cost out loud with the family, then subtract what is genuinely available — savings, payable-on-death accounts, any existing life insurance. What remains is the target. Sometimes the honest answer is that a modest policy plus existing savings covers it. Sometimes the family realizes their current plan leaves a real shortfall. Either answer is better discovered now than by your children later.
For families who want to understand the funeral side of the equation, the Funeral Consumers Alliance offers plain guidance on planning and consumer rights at funeral consumers.org, and the Social Security Administration explains survivor benefits — a separate program from life insurance — at ssa.gov/benefits/survivors. Neither page requires anything of you; both are worth twenty minutes.
Whole life, term, or prepaid funeral: which fits?
| Option | How it works | Best fit when… | Main trade-off |
|---|---|---|---|
| Final expense whole life | Small permanent policy; benefit paid to your beneficiary, who directs the funds | You want a permanent benefit and flexibility in how the money is used | Carrier sets rates based on your health answers; benefit is fixed at issue |
| Term life insurance | Coverage for a set number of years; larger benefit possible for the premium | You need a large amount of protection during a specific period, such as while a mortgage is active | Coverage ends when the term ends, and renewing later may cost more |
| Prepaid funeral plan | Paid directly to a specific funeral home for specified services | You want the exact service arrangements locked in with one provider | Funds are tied to that provider; the benefit does not go to your family to direct |
The one-line takeaway: whole life gives your family flexibility, term gives your budget more protection per dollar while it lasts, and a prepaid plan gives certainty about the service itself — and many families use a combination rather than picking one.
What happens during the application and approval process?
The process is shorter than most people expect. You and Martin go through the health questions together, on the phone or at your kitchen table, so nothing gets misread. The application goes to the carrier. The carrier reviews the answers, sets your rate based on its underwriting rules, and approves or declines the application — that decision belongs entirely to the carrier, and an honest agent will tell you that upfront rather than hint at an outcome.
If the carrier offers a modified rate or a graded benefit because of a health condition, Martin explains exactly what that means before you accept anything. If the carrier declines, he can often look at whether a different type of policy fits better. What he will never do is promise you an approval, because the one thing no agent controls is the underwriting decision itself.
If you are somewhere in this process right now and stuck on a step — a health question you are unsure how to answer, a policy you inherited that you does not locate, a beneficiary form that needs updating — that is a normal place to be, and a ten-minute call to (224) 578-2989 usually untangles it faster than a week of internet searching.
Why do Illinois families choose a local independent agent?
Because the relationship does not end when the application is approved. Martin has served families across the Chicago suburbs and northern Illinois for years — Elgin, Aurora, Naperville, Schaumburg, Rockford, Joliet, Waukegan, Crystal Lake, DeKalb, and the surrounding communities — and many of his clients came to him through a neighbor or a family member who had already worked with him.
Local matters in practical ways. Illinois families deal with Illinois probate timelines, Illinois funeral homes, and Illinois paperwork, and an agent who works in those systems daily can flag issues a national call center does not. When a client passes away, the family calls the same number they always called, and talks to the same person who helped them set the policy up. In a hard week, that continuity counts for more than any feature comparison.
You can read more about Martin's background and the Eichhorn Group's approach on the about page.
What should you prepare before the first conversation?
Five things, none of which take long to gather. Your basic personal information, including date of birth and address. A rough list of your regular medications and any significant health conditions, because the application will ask. The name and contact information of the person you want as beneficiary. A sense of your monthly budget — what premium amount would be comfortable rather than stressful. And your questions written down, because the families who get the most from a first meeting are the ones who ask everything they came to ask.
Martin would rather answer twenty questions than have a client sign anything with a quiet doubt attached. A policy you fully understand is a policy you will keep, and a policy you keep is the one that actually does its job someday.
Families in Elgin and throughout the northwest suburbs often start with the funeral planning question and expand from there — some also review their Medicare supplement options in the same conversation, since both topics tend to surface around the same stage of life.
That is the quiet benefit of working with an independent agent rather than a single-carrier call center: the conversation follows your situation, and when your situation changes, the same person helps you look at it again. If anything here prompted a question, reach out through the contact page or call (224) 578-2989 directly.
Frequently asked questions
Is Golden Memorial an insurance company or an agency?
Golden Memorial is an insurance marketing organization that works with independent licensed agents who offer its product lineup to families. The policy itself is issued by an insurance carrier, which sets the rates and makes the underwriting decision. Martin Eichhorn is an independent licensed agent in Illinois who works with Golden Memorial products and helps clients compare them against their needs. If you want to know exactly which carrier stands behind a specific policy, ask — the agent should be able to name it before you apply.
Do I need a medical exam to qualify for final expense coverage?
Most final expense policies use a health questionnaire instead of a medical exam, which is one reason they appeal to older applicants. The carrier still underwrites the application — it reviews your health answers and decides whether to approve standard rates, offer a modified or graded benefit, or decline. Answering the health questions accurately matters, so Martin walks through them with clients rather than leaving anyone to guess. Every carrier's underwriting rules differ, so two families with similar health histories may receive different outcomes from different carriers.
Who receives the death benefit, and can they use it for anything?
The benefit is paid to the beneficiary you name on the application. That person decides how to use the funds — funeral costs, outstanding bills, or family needs. This flexibility is the main difference between a life policy and a prepaid funeral plan, which ties the money to one funeral home. Naming a beneficiary is worth doing carefully, and Martin reviews beneficiary designations with clients during setup and whenever life circumstances change, such as a divorce, a death in the family, or a new grandchild.
How much does final expense insurance cost in Illinois?
Premiums depend on your age, your health answers, the benefit amount you choose, and the carrier's own rate table — so there is no single number that applies to everyone, and any figure you see quoted online should be treated as an illustration until the carrier makes an actual offer. What Martin does during a first conversation is walk through your situation, describe what different benefit levels have meant for families in similar circumstances, and submit an application so the carrier can give you a real, binding rate. Confirm any fee arrangement with him directly; agents are generally compensated by the carrier.
Can I change or cancel my policy after it is in force?
Yes, within the terms the carrier sets. Beneficiaries can usually be updated with a simple form. Many whole life policies include a grace period for late premiums, and some include a free-look window after issue during which you can reconsider. The specifics live in the policy contract, which is exactly why Martin keeps copies accessible and reviews them with clients periodically. If you hold an older policy through Golden Memorial or another carrier and does not locate the documents, calling the agent who handled it — or (224) 578-2989 if that was Martin — is the fastest route to getting your records in order.
Martin Eichhorn serves families across northern Illinois, including Elgin, Aurora, Naperville, Schaumburg, Joliet, Rockford, Waukegan, Crystal Lake, DeKalb, St. Charles, and communities throughout the Chicago suburbs.
Licensed Insurance Agent · Serving Illinois families for years through the Eichhorn Group and Golden Memorial · Service area: Chicago suburbs and northern Illinois
(224) 578-2989
Golden Memorial and Martin Eichhorn are independent licensed insurance agents. Not affiliated with or endorsed by the government or Medicare. Plan availability varies by area and year. Assistance is provided by a licensed agent.
Planning ahead is easier with someone who has done it hundreds of times. Call Martin at (224) 578-2989 or submit the short form above, and he will walk you through your options — no pressure, plain answers, at whatever pace suits your family.